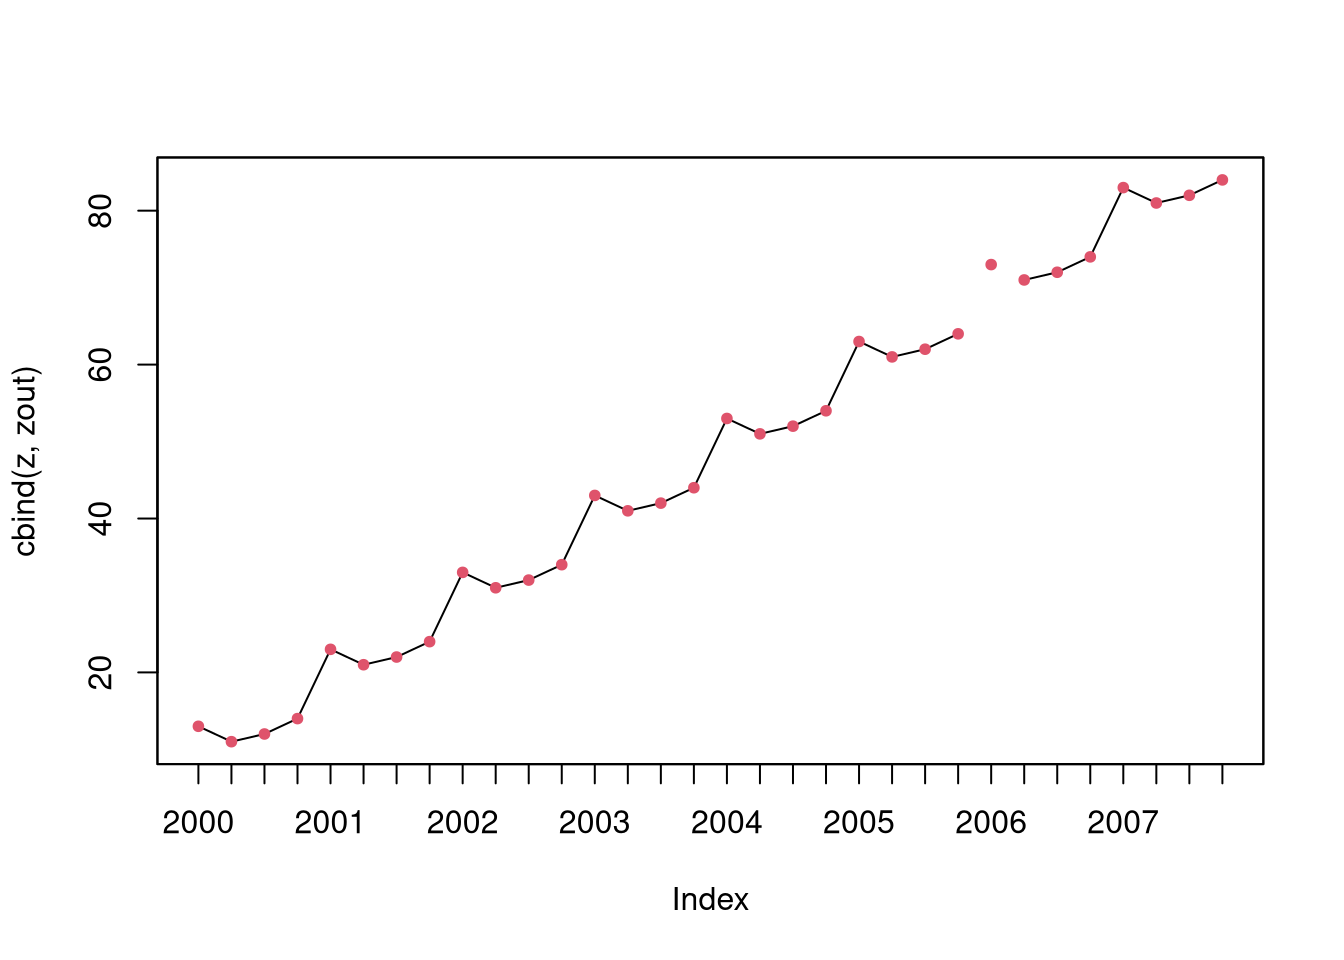
Replace NA by Kalman Filter
Description
Generic function for filling NA values using seasonal Kalman filter.
Usage
na.StructTS(object, ...)
## S3 method for class 'ts'
na.StructTS(object, ..., na.rm = FALSE, maxgap = Inf)
## S3 method for class 'zoo'
na.StructTS(object, ..., na.rm = FALSE, maxgap = Inf)
Arguments
object
|
an object. |
…
|
other arguments passed to methods. |
na.rm
|
logical. Whether to remove end portions or fill them with NA. |
maxgap
|
Runs of more than maxgap NAs are retained, other NAs are removed and the last occurrence in the resulting series prior to each time point in xout is used as that time point’s output value.
|
Details
Interpolate with seasonal Kalman filter, using StructTS, followed by tsSmooth. The input object should be a regular time series and have a frequency. It is assumed the cycle length is 1.
See Also
StructTS, tsSmooth, na.approx